Building a strong financial foundation is one of the smartest steps a company can take for long-term growth. Whether you run a startup, a small company, or an established organization, a strong business financial profile can make it easier to access financing, work with vendors, and separate company finances from personal finances.
In 2026, understanding how business credit works is increasingly important for entrepreneurs who want to grow strategically. A well-managed credit profile can improve financial flexibility and provide opportunities when your company needs additional capital.
What Is Business Credit?
Business credit is a financial record associated with a company rather than an individual. It reflects how a business handles financial obligations such as loans, credit accounts, vendor payments, and other commercial debts.
Similar to personal credit, business credit reports can help lenders, suppliers, and financial institutions evaluate the financial reliability of a company. However, the scoring systems, reporting agencies, and requirements can differ from personal credit.
A strong company credit profile can help demonstrate that your business consistently manages its financial responsibilities.
Why Is Business Credit Important?
A strong credit profile can provide several advantages for growing companies. One of the biggest benefits is improved access to business financing.
When lenders evaluate a company for a loan or line of credit, they may consider its credit history along with revenue, cash flow, time in operation, and other financial information.
Strong business credit may also help with:
- Access to business loans
- Business lines of credit
- Better financing opportunities
- Supplier and vendor relationships
- Higher commercial credit limits
- Separating personal and company finances
- Establishing financial credibility
For entrepreneurs, these benefits can become particularly valuable when expanding operations, purchasing equipment, hiring employees, or managing temporary cash-flow challenges.
How to Build Business Credit
Building a strong credit history does not happen overnight. It requires consistent financial management and responsible use of credit.
1. Establish Your Business Properly
Start by establishing your company as a legitimate business entity. Depending on your situation, this may include registering your company, obtaining an Employer Identification Number (EIN), and opening dedicated financial accounts.
Keeping company finances separate from personal finances is an important foundation for developing a professional financial profile.
2. Open Business Financial Accounts
A dedicated business bank account can make it easier to track company income and expenses. It can also create a clear separation between personal and business transactions.
Consider using a dedicated business credit card for eligible company expenses. Paying the balance responsibly can help establish a positive payment history when the account reports to commercial credit bureaus.
3. Work With Vendors That Report Payments
Some suppliers and vendors report payment activity to commercial credit reporting agencies. Establishing accounts with reporting vendors and consistently paying invoices on time can help create a stronger credit history.
Before opening an account specifically for credit-building purposes, confirm whether the provider reports payment information and which commercial credit bureaus receive the data.
4. Pay Bills on Time
Payment history is an important part of maintaining a healthy company credit profile. Late payments can potentially damage your financial reputation and make future financing more difficult.
Create a reliable system for tracking invoices, loan payments, credit card balances, and recurring expenses. Automated payments and calendar reminders can reduce the risk of missing due dates.
Understanding Business Credit Scores
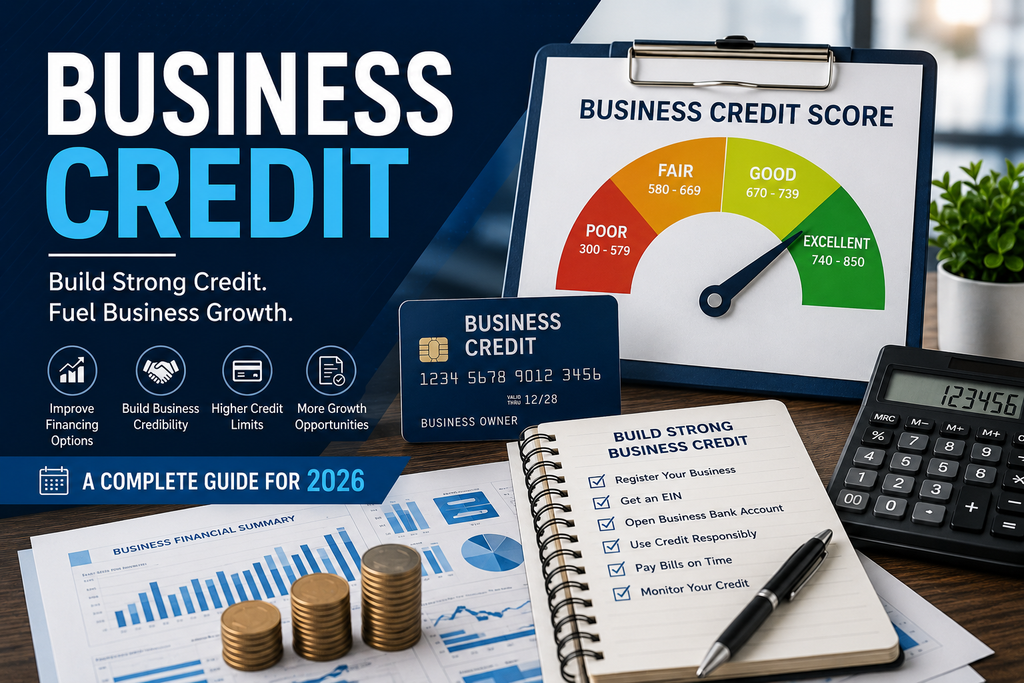
Commercial credit scores are designed to help businesses and financial institutions assess credit risk. Different reporting agencies may use different scoring models and ranges.
Factors can include payment history, outstanding obligations, length of credit history, company information, and other financial indicators.
Because scoring models vary, there is no single number that universally defines whether a company has “good” credit.
The most important objective is to maintain consistent financial behavior: pay obligations on time, avoid unnecessary debt, monitor accounts, and keep company information accurate.
Business Credit vs. Personal Credit
Business and personal credit are separate systems, although they can sometimes overlap.
Personal credit is generally connected to an individual’s financial history, while company credit is associated with the business. Keeping the two separate can provide better financial organization and may reduce the need to use personal accounts for company expenses.
However, new businesses may still encounter situations where lenders request a personal guarantee. This means the owner could remain personally responsible for certain obligations even when the financing is obtained for the company.
Understanding the difference between these two credit profiles can help entrepreneurs make more informed financial decisions.
Common Mistakes to Avoid
Several mistakes can slow the development of a strong commercial credit profile.
Mixing personal and business expenses: Using personal accounts for company purchases can make financial records harder to manage.
Missing payment deadlines: Late payments can negatively affect your company’s financial reputation.
Applying for unnecessary credit: Opening multiple accounts without a clear purpose can create unnecessary financial obligations.
Ignoring credit reports: Errors or outdated information may remain unnoticed if you never review your company’s reports.
Taking on excessive debt: Borrowing should support sustainable growth rather than create financial pressure.
How to Monitor Business Credit
Regular monitoring can help you understand how your company is viewed by lenders and suppliers. Review commercial credit reports for incorrect company details, unfamiliar accounts, inaccurate payment information, or other potential errors.
It is also useful to maintain accurate business records and update company information when necessary.
Monitoring your financial profile does not guarantee approval for future financing, but it can help you identify problems before they become more difficult to resolve.
Final Thoughts
Business credit is an important part of building a financially healthy company. From establishing dedicated accounts to paying vendors on time, small financial habits can contribute to a stronger commercial credit profile over time.
In 2026, entrepreneurs should treat credit management as part of their broader business strategy. A strong financial history can support access to financing, improve vendor relationships, and give companies greater flexibility when new growth opportunities appear.
The key is consistency. Establish your business properly, separate personal and company finances, use credit responsibly, monitor your reports, and make every payment on time. These fundamentals can create a stronger financial foundation for sustainable business growth.